A credit card that went to collections, a salary loan that ran past due, a cancelled card: we hear these stories at the lot from buyers who assume a car loan is off the table. It usually is not. What changes is how much you can borrow, what you need to bring, and what the loan costs. This guide covers what lenders check, what counts as bad credit here, and the four routes that work on a used car budget, with no promise of approval, because nobody honest can make one.
What lenders actually check
A lender approving a used car loan is answering one question: will this borrower pay every month, and if not, will the car cover the balance? Your credit record is one input into that answer, not the whole of it.
- Income and its stability. Payslips and a certificate of employment, or ITR and bank statements for the self-employed. Our car loan requirements checklist lists the documents by borrower type.
- Debt-to-income. Existing amortizations and card minimums against your net monthly income.
- Credit history. The lender's own records plus a credit report from the central registry. This is where bad credit shows up.
- The car. A 2023 Vios is easier to lend on than a fifteen-year-old import, because the lender can recover more if the loan goes wrong.
- Down payment. Your own money in the deal.
- Residence and contactability. Proof of billing and how long you have lived at the address.
Bad credit damages one of those six inputs. Every option below works by strengthening one of the other five.
What bad credit looks like in the Philippines
In the Philippines, bad credit usually means a documented pattern of late or missed payments, not a single slip. The Credit Information Corporation (CIC) is the government-created central credit registry: lenders submit their borrowers' loan records to it and can pull your credit report through an accredited bureau when you apply. What each lender reports and how it scores what it sees varies, so treat this list as the common view rather than a rule.
- Accounts that ran past due for weeks or months, especially in the last two years
- A credit card cancelled for non-payment, or a loan written off
- A previous repossession, or a loan settled for less than the balance
- Collection or court cases over unpaid debt
- Too much active debt for your income, even if every account is current
- No credit history at all: a thin file, which is not bad credit but shows a lender nothing either way
Be honest about which of these is yours. One late payment from two years ago with everything current since is a very different file from an account that is past due today. The second needs settling before any lender looks seriously.
Option 1: a bigger down payment
A bigger down payment is the single most effective move for a buyer with a weak credit file, because it lowers the amount financed and the lender's risk at the same time. Loan-to-value means the loan as a share of the car's price; the lower it is, the less a lender loses if it ever has to repossess and resell.
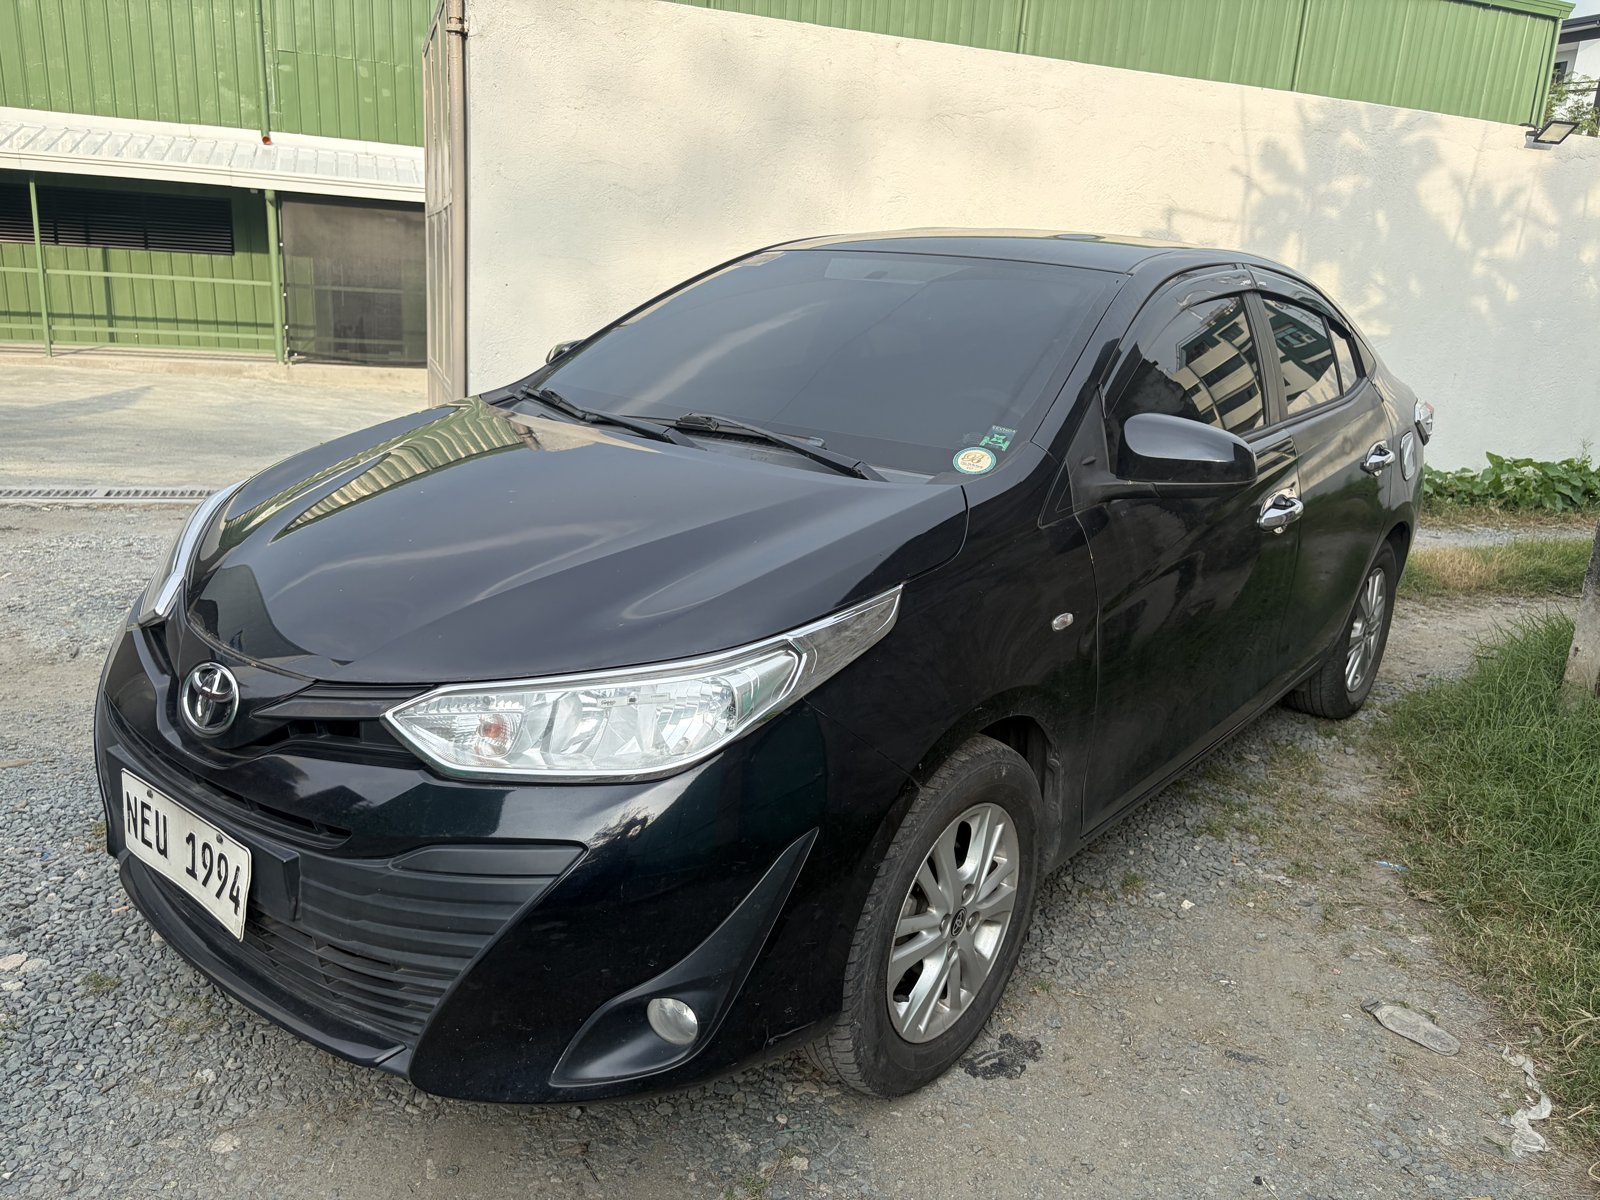
The arithmetic compounds. On the 2019 Toyota Vios 1.3 E MT at ₱250,000, financing ₱150,000 instead of ₱200,000 cuts the one-time 6.95% chattel/processing fee from ₱13,900 to ₱10,425, and cuts add-on interest at 1.40% per month from ₱2,800 to ₱2,100 a month before principal. The lender sees real skin in the game; you see a smaller bill.
The extra money comes from savings, a 13th-month pay, selling your current car, or waiting three more months. Our down payment guide runs the numbers. One warning: do not drain your emergency fund to get there. A loan with no buffer behind it is how good files turn into bad ones.
Option 2: a co-maker or co-borrower
A co-maker is a person with a clean credit record and steady income who signs with you and becomes legally liable if you stop paying. A co-borrower shares the loan as a joint debtor; a co-maker, sometimes called a guarantor, backs it without necessarily owning the car. Lenders use the terms differently, so ask which one they mean.
Typically this is a spouse, parent or sibling with employment or business income, and the lender will ask for their ID, proof of income and proof of billing too. A co-maker helps most when your file is thin or has healed, and least when you still have an open default, because the lender is then being asked to ignore an active problem.
Do not take it lightly on either side. If you miss payments, the lender collects from your co-maker and their credit record carries the damage. Agree in writing who pays what, and tell them early if you hit a rough patch.
Option 3: in-house or dealer-arranged financing
Dealer-arranged financing means the dealer packages your application and sends it to its lending partners, who assess the unit, the down payment, your income and your record together. In-house financing is different: the dealer itself lends the money. Pure in-house loans on used cars are rarer than the ads suggest, and where they exist they tend to cost more, because the dealer carries the full risk.
At RideAgain, financing is arranged through lending partners from 1.40% per month add-on rate, subject to credit approval, with a 6.95% one-time chattel/processing fee on the amount financed. Assessment is fast and the tenor is flexible, but the partners decide, not us. Our financing page has the basics, add-on vs effective rate shows what a monthly add-on really costs, and bank vs dealer financing compares the two routes.
Why this helps a borrower with bad credit is practical. The lender sees the exact car it is lending on, already inspected with documents verified, and you can adjust the unit or the down payment in one conversation instead of reapplying from scratch. One hard rule: walk away from anyone who promises a yes before seeing a single document, or asks for a fee before any assessment. That is a scam with a car in the photo.
| Option | What it changes for the lender | Works best when | The trade-off |
|---|---|---|---|
| Bigger down payment | Lower amount financed and loan-to-value; smaller 6.95% fee and monthly add-on interest | You have savings or a car to sell, and past-due accounts are settled | Less cash buffer after the purchase |
| Co-maker or co-borrower | A second income and a clean record stand behind the loan | Your file is thin or has healed and a relative is willing | Their credit record is on the line if you miss |
| Dealer-arranged financing | The lender assesses unit, down payment and income as one file | You want one application and a fast answer on a specific car | Still subject to credit approval; add-on rate plus the 6.95% fee |
| Cheaper car in cash | No lender involved | Your file has an open default you cannot settle yet | Older or higher-mileage unit; more inspection work |
Option 4: buy a cheaper car in cash
If your file has an active default, the fastest road to a car is often to skip the loan and buy a cheaper unit in cash. No chattel fee, no interest, no co-maker, no annotation on the CR; the car is yours outright when the documents transfer.
Cash buys more than people expect. A 2019 Toyota Vios 1.3 E MT at ₱250,000 is a daily-duty car with cheap parts that any mechanic in Metro Manila can service. Browse every Vios in stock to see the spread by year, or our picks under ₱300k if the budget is tighter. The trade-off is that an older car needs a harder look: every unit we sell is inspected and its documents verified, but it is sold as-is, where-is, so go through it yourself with our engine check guide. The upside is strategic: buy in cash now, pay everything on time, and finance the next car in two years with a clean recent record.
Rebuilding credit in 6–12 months
Credit heals through months of on-time payments, and six to twelve months of a clean record is usually enough to change the conversation with a lender. There is no shortcut, but there is a sequence.
- Settle or restructure every past-due account and keep the clearance letter. This unlocks everything else.
- Pay everything on or before the due date for at least six months. Set up auto-debit so a forgotten bill cannot undo the work.
- Bring card balances down and stop opening new credit; your debt-to-income improves at the same time.
- Keep one small credit line active and paid in full monthly. A closed file shows nothing; a well-handled line shows recovery.
- Build an income paper trail. Route salary or business receipts through one bank account and file your ITR.
- Check your own credit report through a CIC-accredited bureau and dispute anything wrong or already settled.
- Save the down payment in parallel. ₱5,000 a month for a year is ₱60,000 more equity in the deal.
A year later the same lender sees a different borrower. Our how much car can you afford guide helps you size the purchase so the new loan stays comfortable.
Affordable units in stock
The cheapest way to make a loan approvable is to ask for less, and these four units in our Parañaque stock run from a cash buy to a family MPV where the down payment does the heavy lifting.
- 2019 Toyota Vios 1.3 E MT — listed at ₱250,000 (October 2026): the cash-buy candidate, or a very small loan.
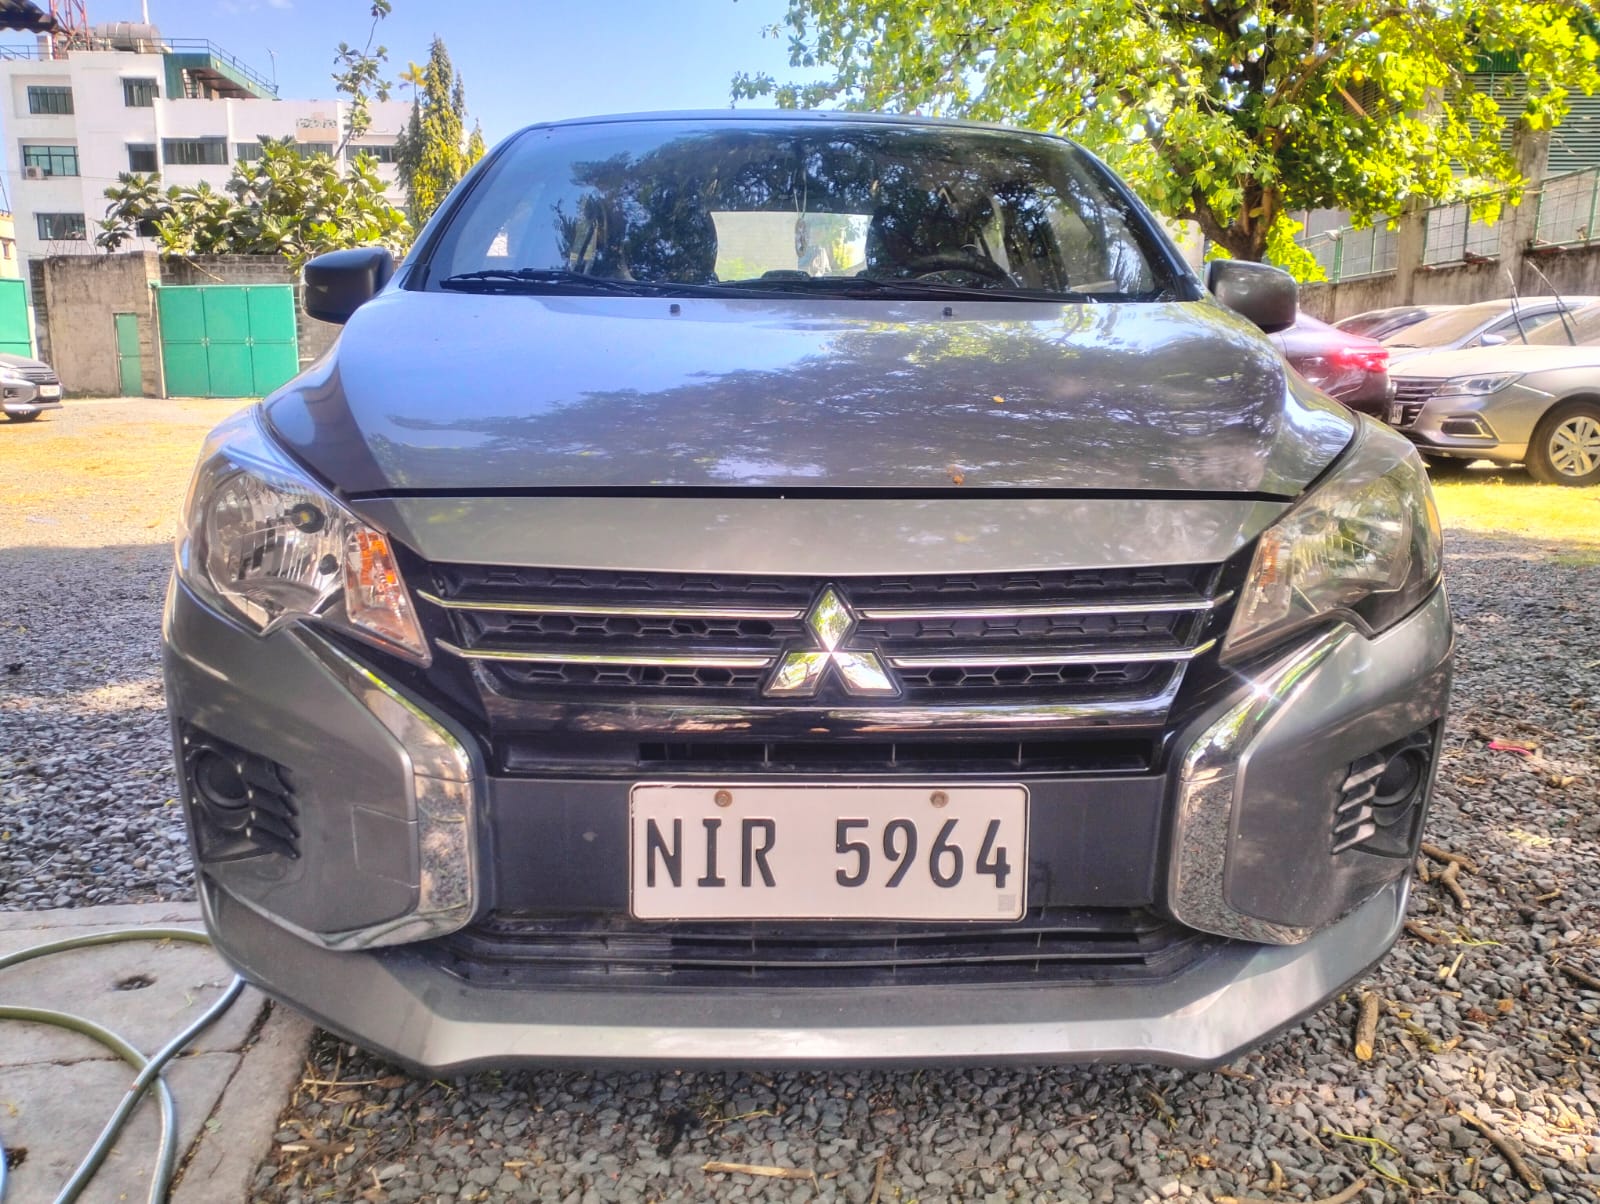
- 2023 Mitsubishi Mirage G4 GLX 1.2G CVT — listed at ₱395,000 (October 2026): a late-model automatic with low running costs.
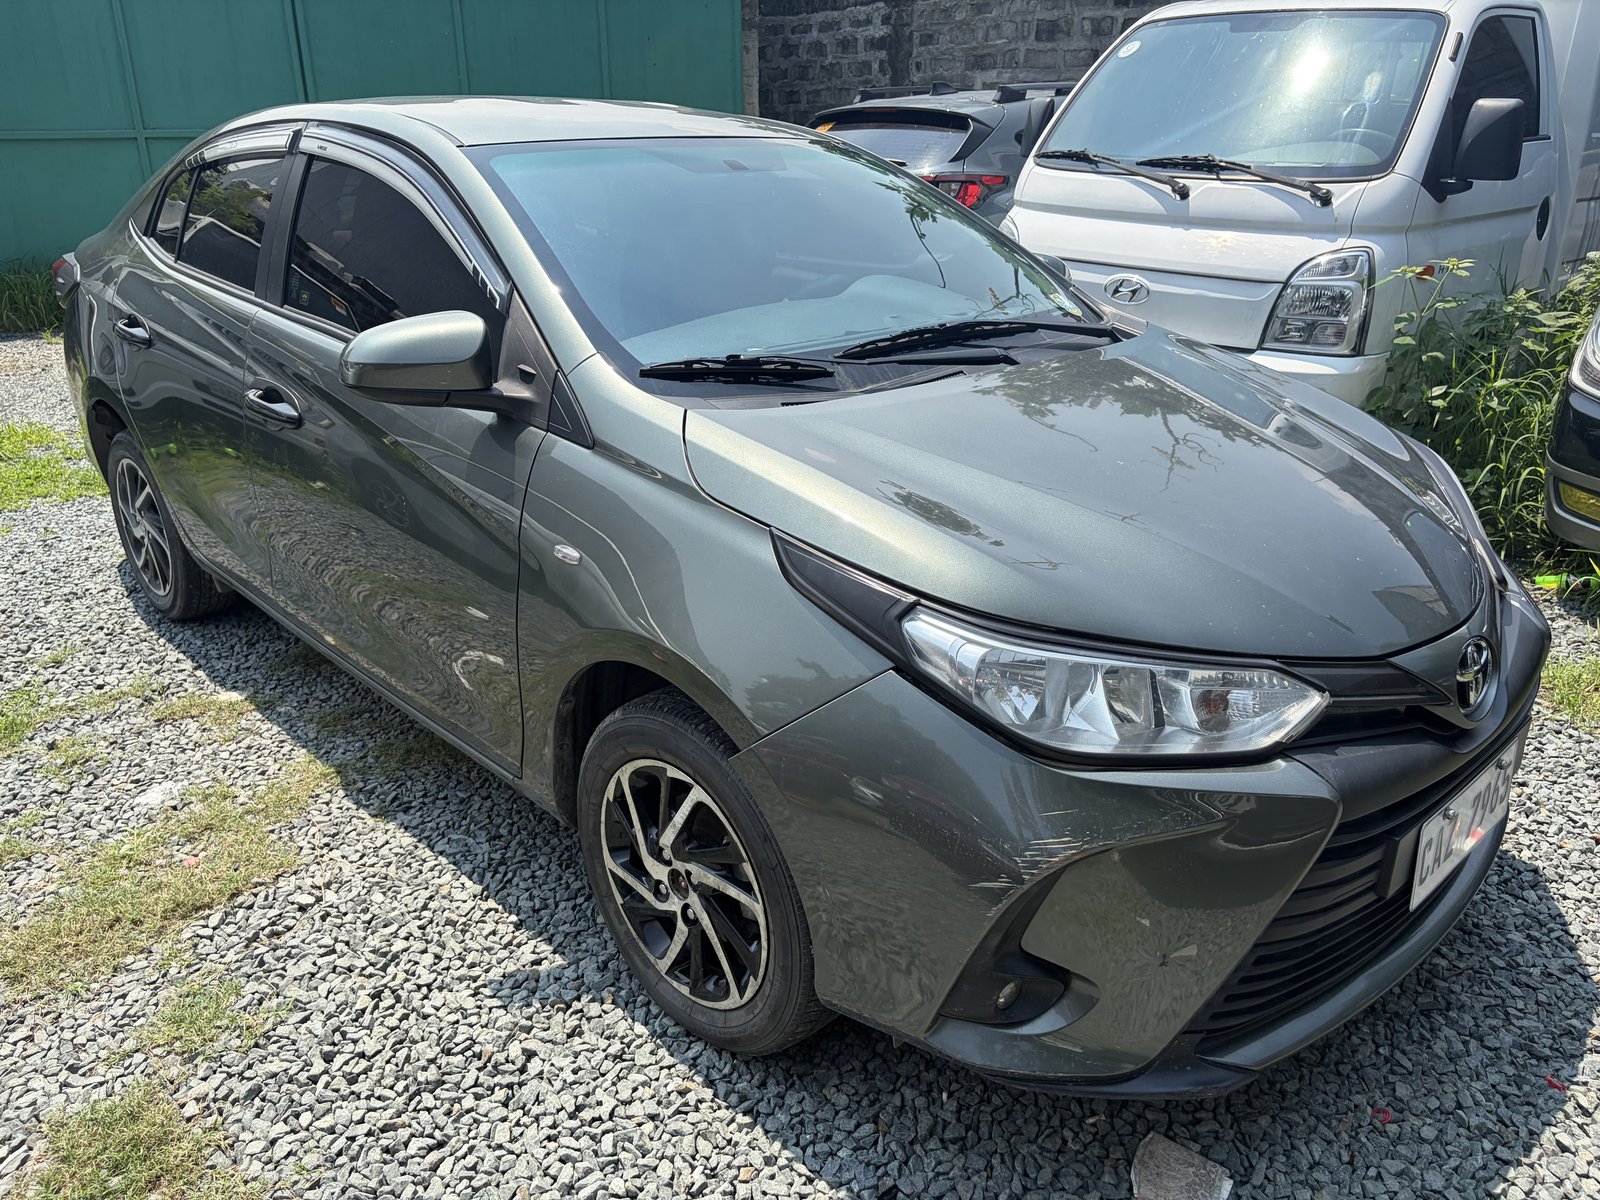
- 2023 Toyota Vios 1.3 XLE CVT — listed at ₱495,000 (October 2026): strong resale demand, which lenders like.
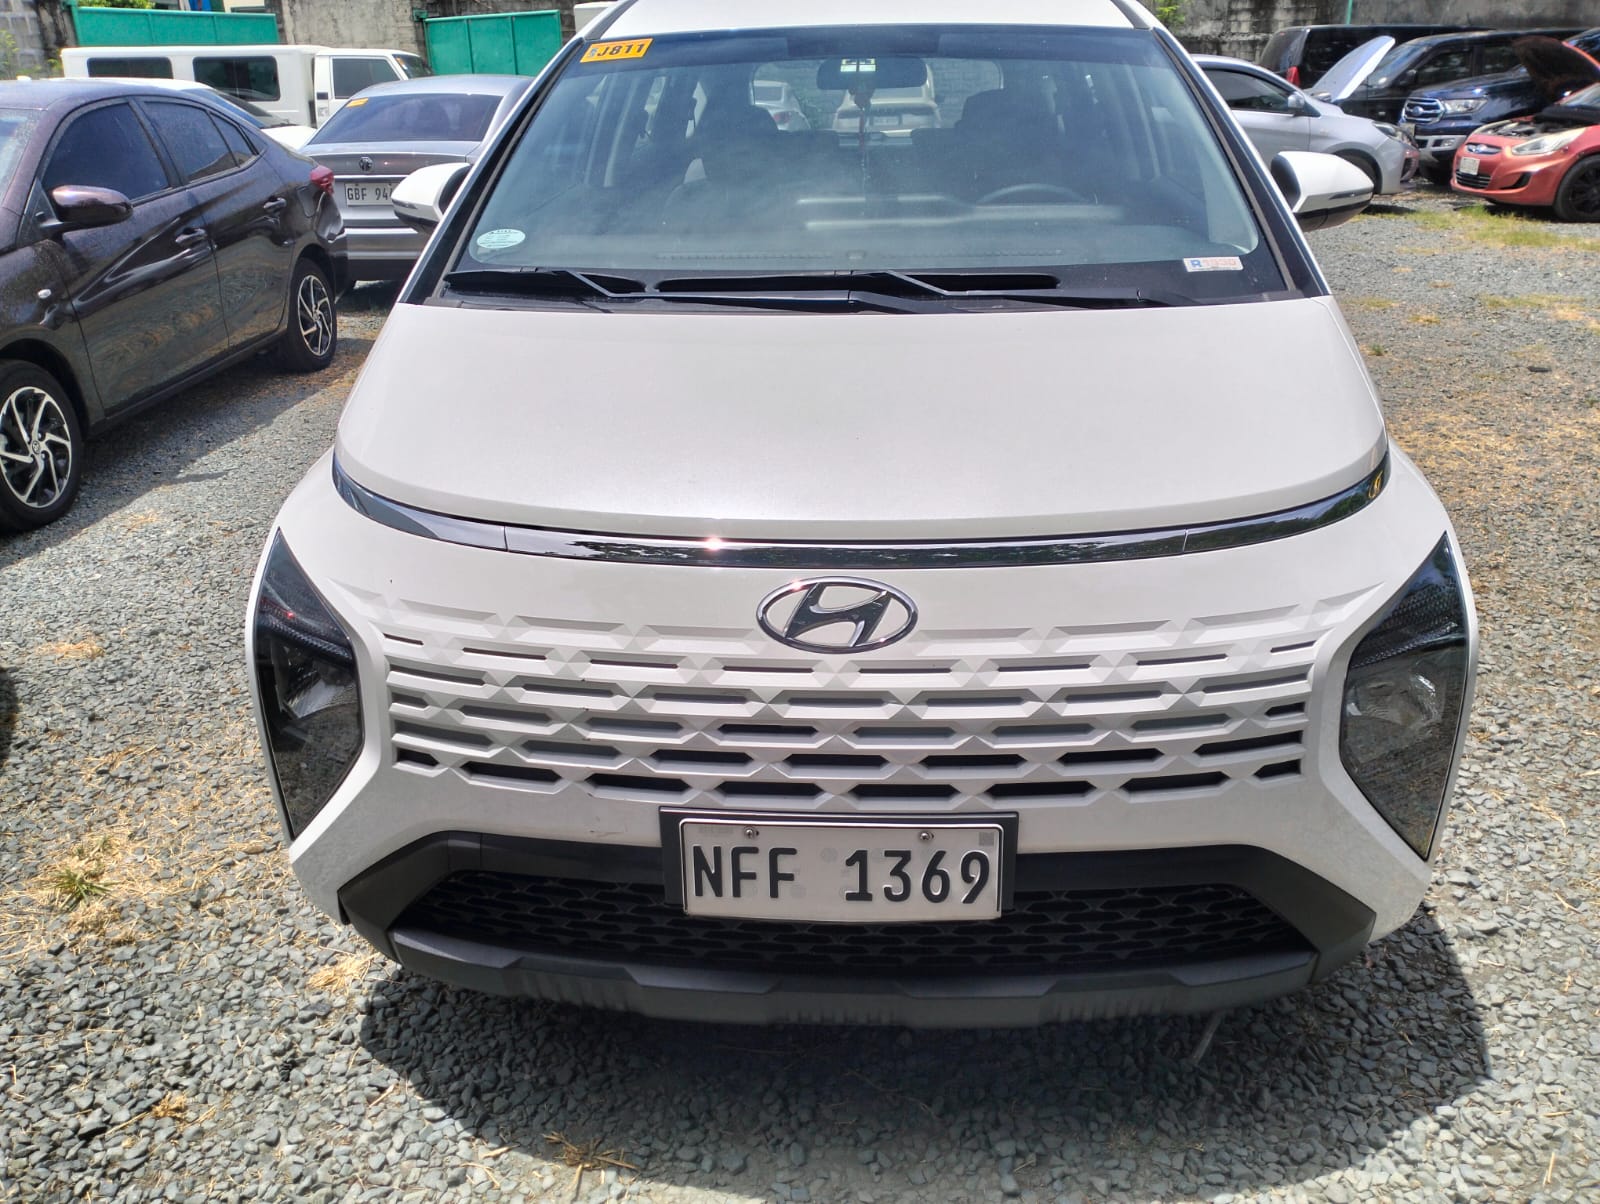
- 2024 Hyundai Stargazer GL IVT — listed at ₱570,000 (October 2026): a seven-seater where a bigger down payment matters most.
How it works here: send a private offer on the unit you want, tell us you need financing, and we run the assessment with our lending partners. Full payment comes before release, and the OR/CR and transfer documents follow two to four weeks after; how it works has the full flow. Viewings are by appointment, Monday to Saturday, 9 AM to 6 PM, at Vitalez Compound, Parañaque City. Call, WhatsApp or Viber +63 931 209 9607, or book a viewing online.
FAQ: car loans with bad credit
Can I get a car loan with bad credit in the Philippines?
Sometimes, but never as a certainty. Lenders weigh your credit record against your income, your down payment, a co-maker if you have one, and the car itself. A bigger down payment, a creditworthy co-maker and a newer, in-demand unit all improve your odds. Settle any account that is still past due first; financing at RideAgain is subject to credit approval like any other loan.
What is considered bad credit in the Philippines?
Bad credit usually means a documented pattern of late or missed payments: accounts that ran past due for months, a credit card cancelled for non-payment, a default or write-off, a repossession, or a debt case. Lenders see these through their own records and credit reports from the Credit Information Corporation registry. Having no credit history at all is a thin file, a different and easier problem.
Does a bigger down payment help with bad credit?
Yes, more than any other single factor. A larger down payment lowers the amount financed, so the lender's loss if you default is smaller, and it also cuts the 6.95% chattel/processing fee and the monthly add-on interest you pay. It does not erase an open past-due account, so settle that first, and keep some savings as a buffer after you buy.
Can a co-maker help me get approved?
Often, yes. A co-maker with steady income and a clean credit record gives the lender a second person to collect from, which offsets a thin or recovering file. It helps less when you still have an active default. Choose someone who understands they become legally liable for missed payments, and put your repayment agreement in writing before either of you signs.
How can I rebuild my credit before applying?
Settle or restructure every past-due account and keep the clearance letter, then pay every bill on time for six to twelve months, ideally by auto-debit. Lower your card balances, keep one small credit line active and fully paid, avoid new loans, and keep income flowing through one bank account. Check your own credit report through a CIC-accredited bureau and dispute any errors.